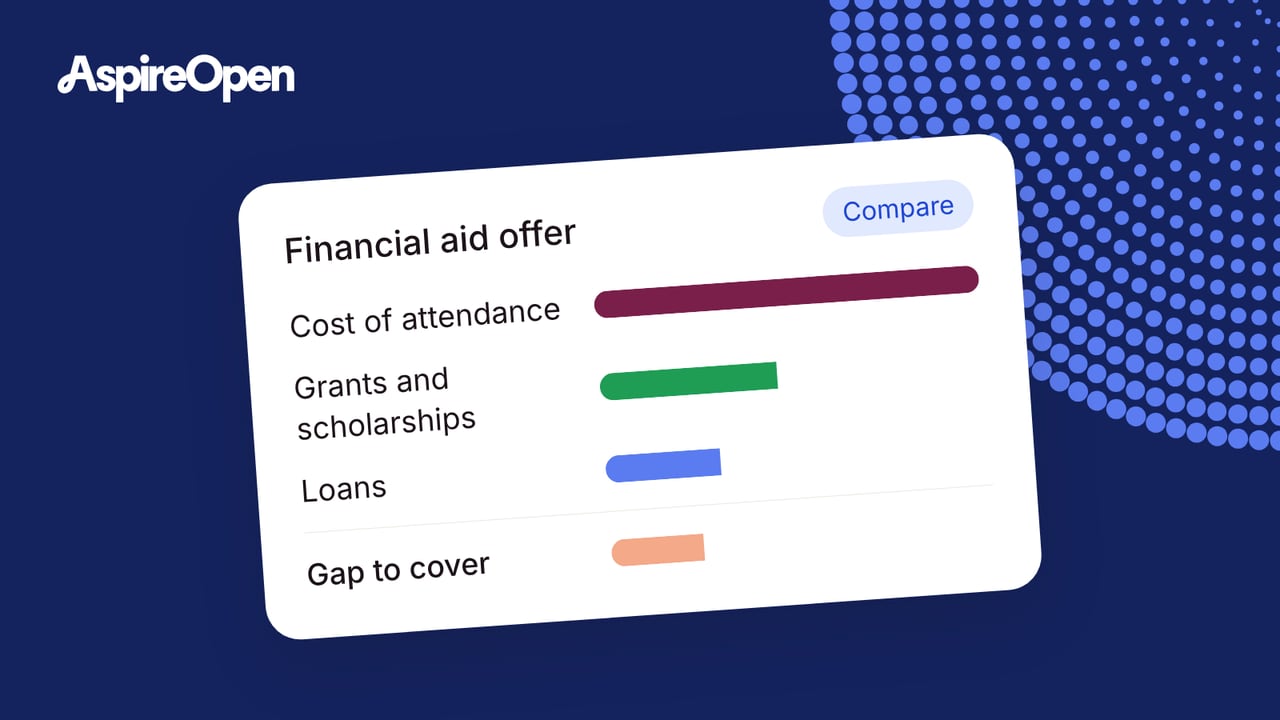
To pay for college, first estimate the full cost, subtract confirmed grants and scholarships, then decide how to cover the remaining gap with available resources and any borrowing you are prepared to repay. Do not start with a loan amount or assume that an impressive aid total makes a school affordable.
This guide provides a planning sequence, not a recommendation to borrow a particular amount. Official resources were checked October 13, 2026; school-specific deadlines and terms still need direct confirmation.
Step 1: Price the year you will actually attend
Create two lists. The first contains charges billed by the school, such as tuition and applicable fees or housing. The second contains expenses you may pay elsewhere, such as books, transportation, and off-campus living costs. Use the school’s current cost-of-attendance breakdown and replace estimates with your own realistic costs where appropriate.
Before admission, use each college’s net price calculator as an estimate. After admission, use the actual aid offer and confirm the matching year, enrollment level, and housing assumptions. Federal Student Aid’s offer-evaluation guide explains why total cost and net price need separate attention.
Step 2: Apply for aid without guessing eligibility
Complete the appropriate year’s FAFSA and check each school’s and state’s additional requirements. Federal, state, and college deadlines may differ; the federal deadline is not a safe substitute for the earliest deadline affecting you. Record the deadline, required form, and submission confirmation in one checklist.
The FAFSA Submission Summary is not the school’s final aid offer. Review it for issues or required follow-up, then wait for or request the school’s actual package. If a material financial change is not reflected in the application, ask the financial aid office how to request review.
Step 3: Separate money by what it requires
Use four columns: grants and scholarships, earned wages, family or personal resources, and loans. Federal Student Aid recommends accepting grants and scholarships first, then considering work-study and borrowing.
Work-study is not an immediate discount on the tuition bill. You must obtain a qualifying job and earn wages. Consult the work-study guide and the school’s hiring process before treating the offered amount as a certain resource.
For scholarships, confirm whether the award is one-time or renewable and what conditions apply. For loans, identify the borrower and check the current terms rather than counting debt as a price reduction.
Step 4: Calculate the gap with a worked example
The following numbers are hypothetical, not actual school prices or federal loan limits.
| Planning item | Annual amount |
|---|---|
| Total attendance budget | $30,000 |
| Confirmed grants and scholarships | −$12,000 |
| Net price before financing | $18,000 |
| Available savings/family contribution | −$6,000 |
| Realistic wages allocated to college costs | −$2,000 |
| Remaining amount needing a plan | $10,000 |
An offered $10,000 loan would finance that remainder; it would not make the school cost $0. If wages arrive during the semester, you also need to know how to meet any bill due before those earnings arrive.
Step 5: Solve timing as well as total cost
Ask the billing office when payment is due, when confirmed aid is expected to disburse, and whether an installment plan is available with fees you can afford. Ask the financial aid office whether an outside scholarship changes other aid. Get school-specific answers rather than assuming one institution’s policy applies everywhere.
If the gap is still unmanageable, compare a lower net-price school, a different housing plan, or another enrollment pathway. Verify credit transfer and degree requirements before assuming a cheaper first year automatically produces a cheaper degree.
Step 6: Recheck every year
Build a separate budget for later years. A renewable award is only as dependable as its stated conditions and your ability to meet them. Use a conservative scenario that removes unconfirmed future scholarships and includes known changes in expenses.
Your next move is a one-page plan: total budget, confirmed gift aid, available resources, financing considered, payment dates, and unanswered questions. Take that sheet to the college’s financial aid office before committing to an unaffordable gap.