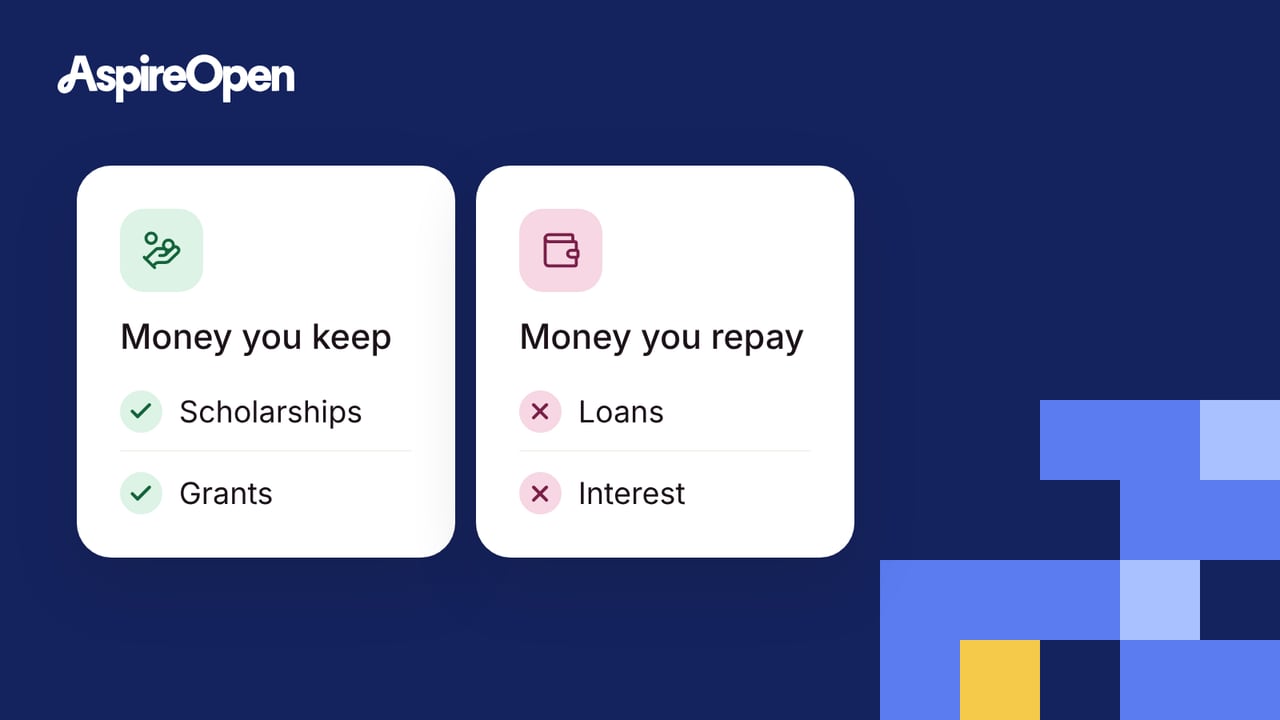
Read a financial aid award letter by separating grants and scholarships from loans and work-study, then subtracting only grants and scholarships from the full attendance budget to find net price. Next, identify how you would pay that net price and when money would become available.
A financial aid offer is a school’s statement of the types and amounts of aid it is offering you. Your FAFSA Submission Summary is not that offer. Federal Student Aid explains the difference in its financial aid dictionary.
First check the assumptions
Find the academic year, number of terms, enrollment level, and housing arrangement used in the offer. A semester figure and an annual figure cannot be compared directly. If you plan to commute but the budget assumes campus housing, ask the school how both the budget and aid would change.
Also check whether an amount is confirmed, estimated, conditional, or awaiting documentation. Do not treat an incomplete package as the final price. Keep the school’s written answers alongside the offer.
Sort every item into a category
| Category | How to read it | Follow-up question |
|---|---|---|
| Grant or scholarship | Gift aid, subject to its terms | Is it renewable, and what conditions apply? |
| Student loan | Money borrowed by the student | What amount is being offered, and what are the current costs and conditions? |
| Parent borrowing | Financing involving a different borrower | Is this merely an option shown, or an approved borrowing arrangement? |
| Work-study | Potential wages from qualifying employment | How do I find a job, and when would wages arrive? |
| Cost of attendance | A budget, not necessarily the amount billed | Which costs are billed by the school and which are estimated personal expenses? |
Work-study requires obtaining work and earning wages; it is not a guaranteed upfront tuition payment. Read Federal Student Aid’s work-study guidance before putting its full offered amount into a bill-payment plan.
Calculate net price before financing
Use the method in Federal Student Aid’s offer-evaluation guide: full attendance cost minus grants and scholarships. Loans may cover that cost, but they do not lower the price.
Here is a hypothetical offer, not a real college package or a statement of federal loan limits:
| Item | Annual amount |
|---|---|
| Attendance budget | $28,000 |
| School scholarship | $7,000 |
| Other confirmed grant | $5,000 |
| Net price | $16,000 |
| Loan listed separately | $5,000 |
| Potential work-study wages | $2,000 |
The net price is $16,000, not $9,000. The loan is financing; the wages would have to be earned. A student still needs a plan for the entire $16,000 and for the timing of payments.
Identify what the offer does not explain
An offer can omit the practical detail you need most. Ask about scholarship renewal, fees not reflected in the visible total, outside scholarship coordination, and outstanding verification documents. Do not assume an outside scholarship always adds its full amount to existing gift aid; request the school’s actual policy.
If household finances changed, ask the financial aid office about review procedures and supporting documents. The CFPB financial aid office guide explains the office’s role in helping students understand aid options.
Use a concise follow-up message
“I’m reviewing my aid offer for (your academic year). Please confirm whether the amounts cover the full year, which awards are renewable, and which costs are not billed by the school. I also received an outside scholarship; how would it affect this package? Please tell me whether any documents remain outstanding.”
Adapt the brackets and remove questions the offer already answers. Do not send account passwords or unnecessary sensitive documents by ordinary email; use the school’s stated submission process.
What should you accept first?
Federal Student Aid recommends considering grants and scholarships first, followed by work-study and then loans. Read each item’s conditions before accepting it. The goal is not to accept the largest package; it is to understand the lowest workable cost and any obligations you would take on.